

Blog Detail
Smart Home Loan Planning in Kerala: Maximizing Tax Benefits on Ready vs Under-Construction Homes
Posted onNov 10, 2026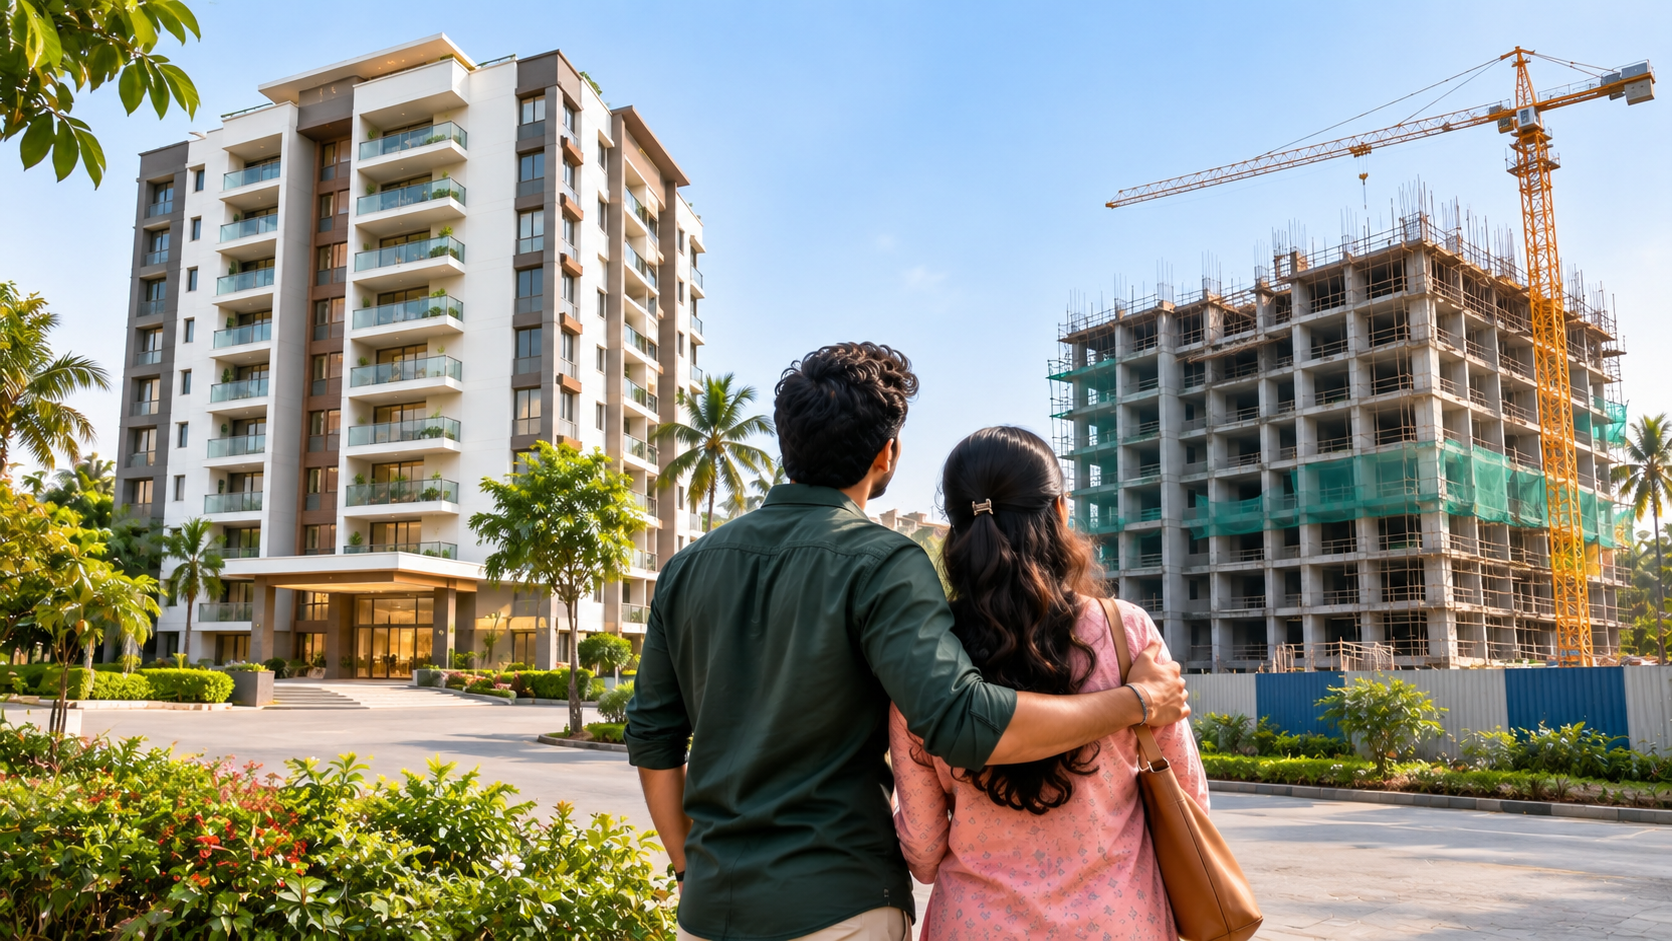
Ask any family house-hunting in Thrissur what worries them most, and the answer is almost always the EMI. Will it fit the monthly budget? Will it crowd out school fees and the Onam shopping? Fair questions. But there's a second one that rarely gets asked until March, when the tax-filing scramble begins: what is this loan doing to my tax bill?
That is the heart of Smart Home Loan Planning in Kerala. Two buyers can borrow the same amount, yet one ends up saving far more tax simply because of the kind of home they chose, ready or still under construction. Here's how it plays out.
The two deductions that matter
Most of the saving comes from two places. The first is interest. If you live in the flat yourself, you can deduct up to ₹2 lakh of interest a year under Section 24(b), which appears as Section 22 in the new Income-tax Act, 2025. The second is principal. The portion of your EMI that repays the loan counts under Section 80C, up to ₹1.5 lakh a year, though that limit is shared with your PF, life insurance premium and children's tuition fees. Stamp duty and registration charges also count under 80C in the year you pay them.
There's one catch. For a home you live in, these deductions are available only if you file under the old tax regime. The new regime allows no interest deduction on a self-occupied house. So run the numbers both ways before you decide.
Ready homes: the simple route
With a ready flat, there's nothing to wait for. Your EMIs start, and so do your claims, in the same year. Keep the lender's annual interest certificate safe and your CA has everything needed. If certainty matters more to you than anything else, this is the cleaner path.
Under-construction homes: patience, with conditions
Buy a flat that's still being built and the rules shift a little. First, you can't claim interest while the building is going up. That money, called pre-construction interest, is held back and claimed after you receive possession, in five equal yearly instalments starting from the year of completion. Second, the 80C deduction on principal also waits until possession.
Here's a quick example. Say you pay ₹3 lakh in interest during construction. After handover, you can claim ₹60,000 a year for five years. If your regular interest in one of those years is ₹1.8 lakh, the total comes to ₹2.4 lakh, but the ceiling for a self-occupied home is ₹2 lakh, so ₹40,000 goes unused. The Union Budget 2026 confirmed that this treatment carries over into the new Income-tax Act, 2025.
Mind the clock, too. To enjoy the full ₹2 lakh limit, construction must finish within five years from the end of the financial year in which you took the loan. Miss that window and the interest deduction shrinks to ₹30,000 a year. A builder's delivery record, then, isn't only a comfort issue. It's a tax issue.
Smart moves before you sign
- Borrow jointly. If you and your spouse are both co-owners and co-borrowers, each of you can claim the interest and principal deductions separately, which can nearly double the benefit.
- Ask for a split certificate. Request a statement from your bank that separates pre-construction interest from interest paid after possession.
- Pick a builder who delivers on time. When you shortlist apartments in Thrissur, check for RERA registration and past handover dates.
- Review your regime every year. Your income, investments and loan stage change, so the better option can change as well.
Tax rules get revised often, so do confirm the latest position with a chartered accountant before filing.
Frequently Asked Questions
How much tax can I save on a home loan in Kerala?
Under the old tax regime, you can deduct up to ₹2 lakh of interest and ₹1.5 lakh of principal a year on a self-occupied home. At the 30% slab, that can be worth roughly ₹1 lakh a year, depending on your other 80C investments.
Can I claim a tax benefit on an under-construction flat?
Yes, but only after you get possession. Interest paid during construction is claimed in five equal yearly instalments, and the principal deduction begins after possession too.
What is pre-construction interest?
It is the interest you pay on your home loan from the date you borrow until the end of the financial year before the one in which construction is completed.
Is home loan interest deductible in the new tax regime?
Not for a house you live in. In the new regime, the interest deduction is available only for a rented-out property.
Is a ready flat better than an under-construction one for tax savings?
A ready flat gives you benefits right away, while an under-construction one delays them. The ₹2 lakh interest cap is the same either way, so choose based on your budget and how soon you need to move in.
Where can I find apartments in Thrissur from a trusted builder?
Varma Homes can show you available apartments in Thrissur and help you match the handover timeline to your loan plan.
Plan your home, and your loan, with Varma Homes
A well-planned loan can put real money back in your pocket every year. The right home makes that plan work. Talk to Varma Homes today to explore apartments in Thrissur that fit your budget, your timeline and your tax strategy.